
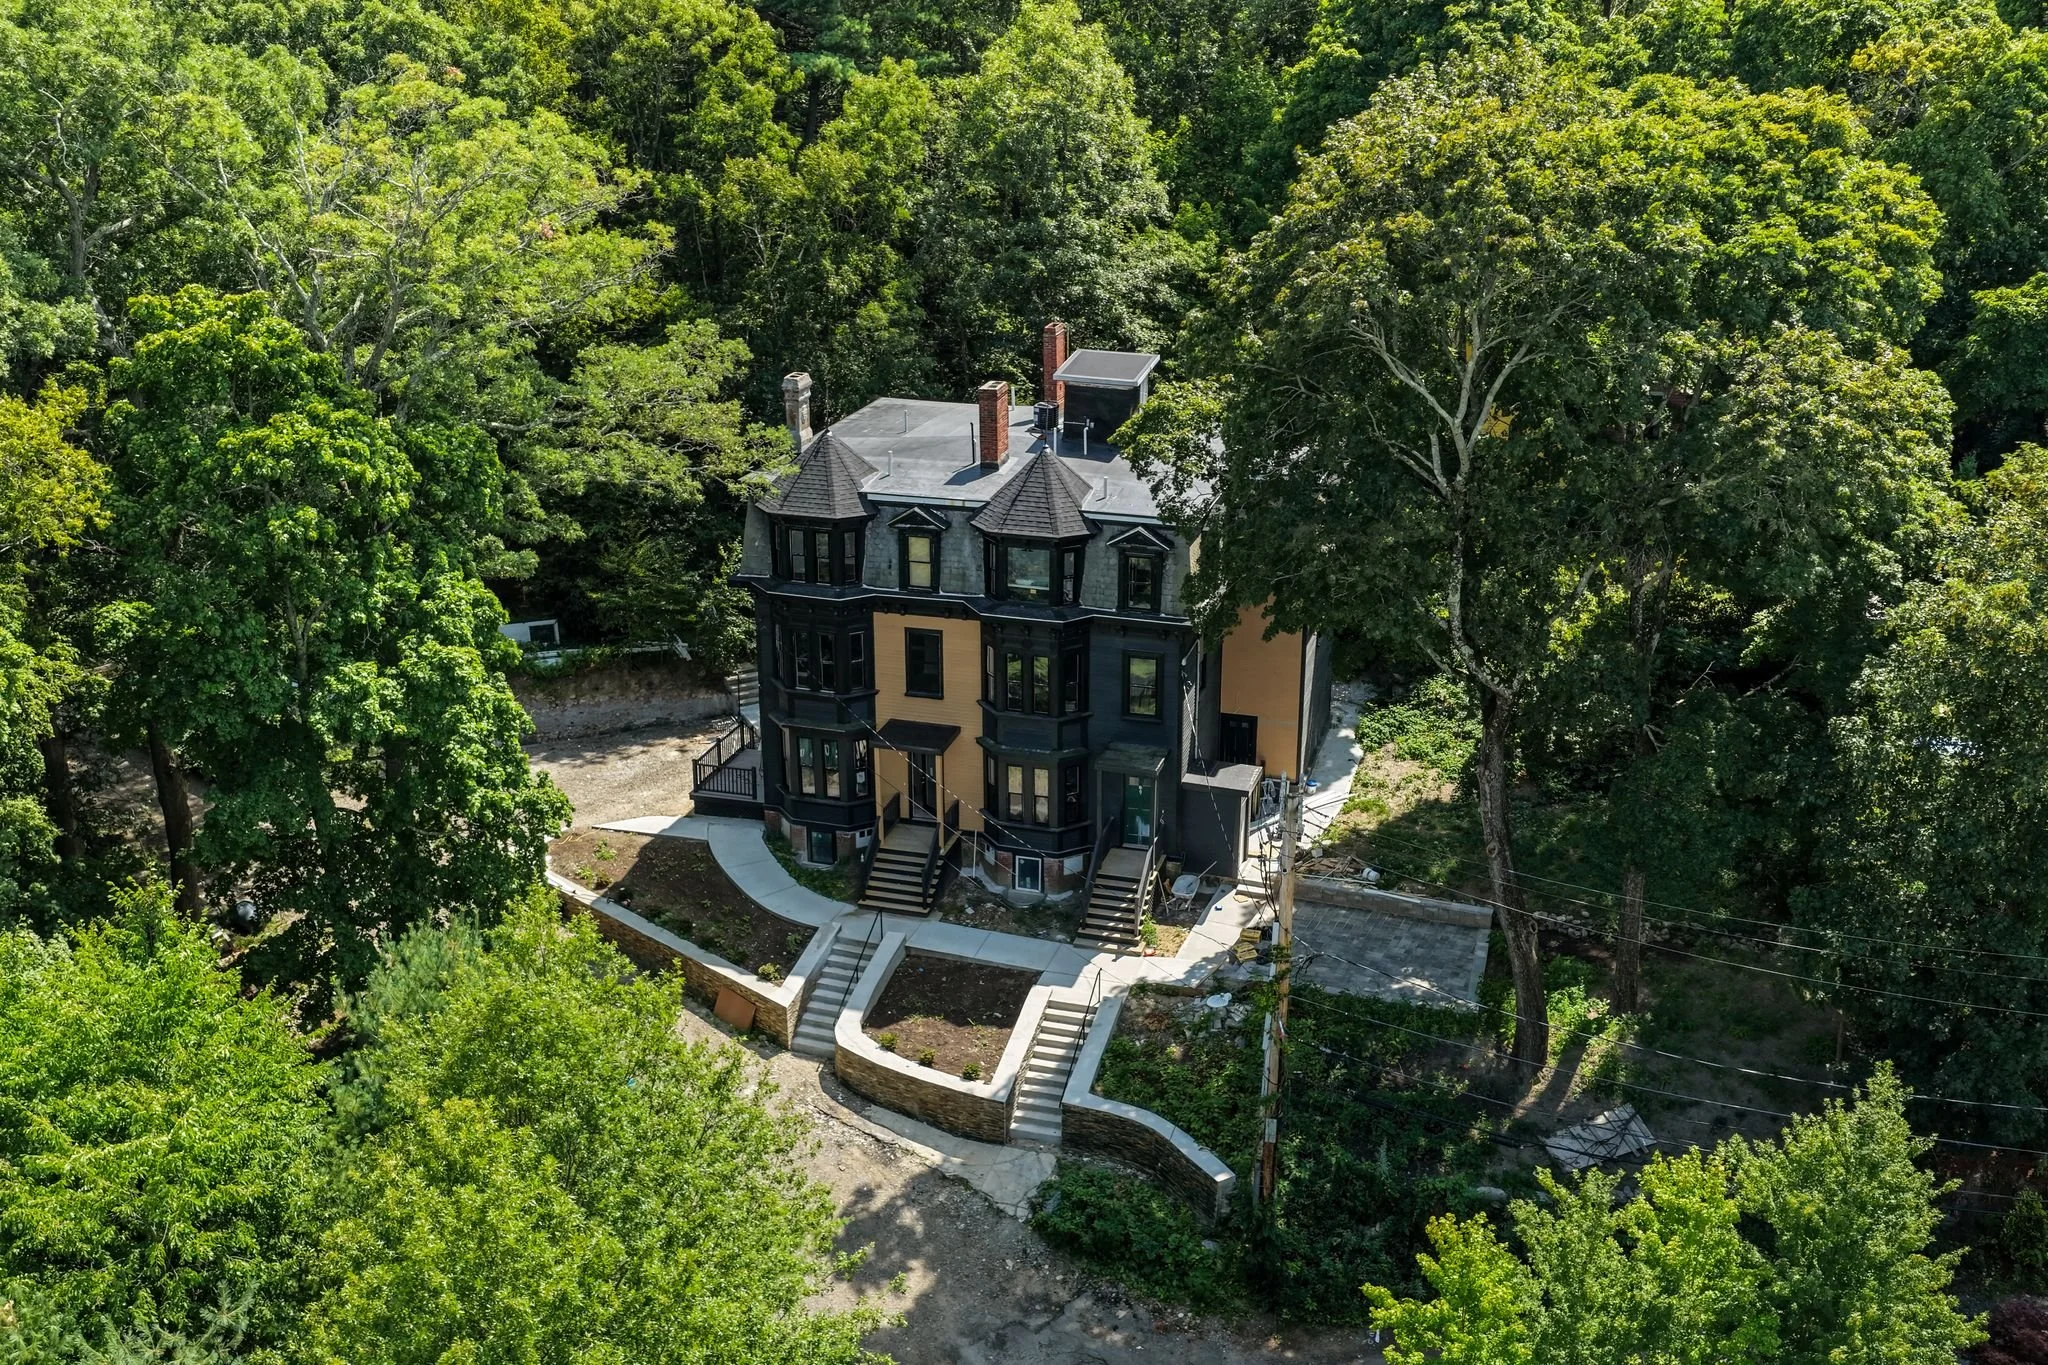
A home you love.
More room in your monthly budget.
A permanent mortgage rate buydown could make your next home more comfortable to own. Explore how a seller credit may help lower your fixed interest rate and monthly principal and interest payment.
Available terms depend on the home, the negotiated seller contribution and your financing. These examples are a starting point for a conversation.
potential monthly principal & interest savings
Illustrative $900,000 purchase · 10% down ($90,000) · $810,000 loan · 360 monthly payments · fixed interest rate 5.625% / annual percentage rate (APR) 5.682%. Assumed comparison rate: 7.625%; not a current market quote. Illustrated seller credit: $60,000. Taxes, insurance, condo fees and mortgage insurance are additional.
Less interest.
More breathing room.
A seller-funded permanent buydown uses an agreed-upon credit at closing to help pay discount points. Those points can reduce the interest rate on your fixed-rate mortgage for as long as you keep that loan.
Start with the right fit.
Explore the Yale Terrace homes and talk with us about the seller contribution that could be included in an offer.
Get your own numbers.
A lender confirms your eligibility, loan program, allowable credit, available rate and total monthly housing payment.
Keep the benefit over time.
Unlike a temporary buydown, the reduced fixed rate lasts for the life of that loan. Selling or refinancing ends that loan and its rate.
View The Residences
16-18 Yale Terrace #1
BD | BA | SQFT
Offered for: $
16-18 Yale Terrace #2
BD | BA | SQFT
Offered for: $
18 Yale Terrace #2
BD | BA | SQFT
Offered for: $
What could your payment look like?
Choose a home and down payment to compare the illustrated principal and interest payments. These are financing examples, not available rate quotes or approved seller offers.
- Your down payment
- $90,000
- Loan amount
- $810,000
- Illustrated seller credit
- $60,000
- Assumed loan term
- 30 years · 360 payments
$12,844 in the first 12 months, if the illustrated terms apply
Principal and interest only. Property taxes, homeowners insurance, condo fees and any mortgage insurance are extra. Your total monthly payment will be higher.
Request my personalized numbers ↗Assumed comparison interest rate: 7.625%. This is not a verified current market rate. Both payments use the same $810,000 loan amount and 360-month term.
| Home | Price | Down payment | Loan amount | Seller credit | Fixed rate / APR | Monthly P&I | Monthly savings |
|---|---|---|---|---|---|---|---|
| 16 Yale · Unit 1 * | $850,000 | 10% / $85,000 | $765,000 | $60,000 | 5.625% / Pending | $4,403.77 | $1,010.85 |
| 16 Yale · Unit 1 * | $850,000 | 20% / $170,000 | $680,000 | $60,000 | 5.500% / Pending | $3,860.97 | $952.03 |
| 16 Yale · Unit 2 | $900,000 | 10% / $90,000 | $810,000 | $60,000 | 5.625% / 5.682% | $4,662.82 | $1,070.31 |
| 16 Yale · Unit 2 | $900,000 | 20% / $180,000 | $720,000 | $60,000 | 5.500% / 5.564% | $4,088.08 | $1,008.03 |
| 18 Yale · Apt. 1 | $775,000 | 10% / $77,500 | $697,500 | $50,000 | 5.500% / 5.556% | $3,960.33 | $976.53 |
| 18 Yale · Apt. 1 | $775,000 | 20% / $155,000 | $620,000 | $60,000 | 5.375% / 5.438% | $3,471.82 | $916.50 |
| 18 Yale · Apt. 2 | $1,050,000 | 10% / $105,000 | $945,000 | $60,000 | 5.625% / 5.676% | $5,439.95 | $1,248.70 |
| 18 Yale · Apt. 2 | $1,050,000 | 20% / $210,000 | $840,000 | $60,000 | 5.375% / 5.431% | $4,703.76 | $955.48 |
All examples assume 360 monthly payments over 30 years. Taxes, insurance, condo fees and any mortgage insurance are additional. Savings compare against assumed rates of 7.625%, except 18 Yale Apt. 2 with 20% down (7.125%); these are not current market quotes. All terms and seller credits need confirmation. * 16 Yale Unit 1 is recalculated at $850,000 using the old rates; its rate, credit and APR require a new lender illustration. On small screens, scroll the table horizontally.
Based on the supplied November 6, 2026 illustrations, with principal and interest recalculated assuming fully amortizing, 30-year fixed loans. Credit amounts are illustrative and may exceed what a particular loan program allows. The lender must confirm the term, rates, APRs, points, credit allocation and eligibility. A seller credit is not cash back to the buyer and does not replace the required down payment.
Before you make
your next move.
What makes the buydown permanent?
It reduces the fixed interest rate for the full term of that loan, rather than subsidizing payments for only the first one, two or three years. If you refinance, your new loan will have its own rate and terms.
Will my whole monthly payment stay the same?
The principal and interest payment on a fully amortizing fixed-rate loan generally stays the same. Property taxes, insurance, condo fees and mortgage insurance can change. These examples show principal and interest only.
Can I use the seller credit for my down payment?
The credit is intended for lender-approved closing costs, including eligible discount points. You still need to provide your down payment and satisfy the lender’s cash-to-close and qualification requirements.
Why compare 10% and 20% down?
A 10% down payment keeps more cash available at closing, but means a larger loan and may require mortgage insurance. With 20% down, you borrow less. The supplied illustrations also use slightly lower interest rates with 20% down. Ask your lender to compare the complete costs.
Is the illustrated credit guaranteed?
No. A seller contribution must be negotiated and included in an accepted purchase agreement. The lender must also confirm that the amount and how it is used meet the selected loan program’s requirements. Rates and home availability can change.
How do I know if this is right for me?
Compare a lender’s written Loan Estimates, including your cash to close, points, APR and full monthly payment. Ask about alternatives, such as a different seller credit or purchase price, and consider how long you expect to keep the loan.
Let’s find your
comfortable number.
Tell us which home you’re considering. We can discuss the property and help coordinate a personalized financing conversation with a lender.
Illustration details & important information
Draft for review, prepared November 9, 2026. No financing offer is being made. Rates, APRs, seller contributions, loan terms and availability have not been confirmed for marketing. No rate is locked or guaranteed. The $850,000 illustration for 16 Yale Unit 1 is a mathematical update only; APR is intentionally withheld pending lender recalculation. All other APRs are reproduced from the supplied illustrations and have not been independently calculated.
All examples assume a 30-year fixed-rate, fully amortizing loan with 360 monthly principal and interest payments and no balloon payment. The comparison rate is 7.625% except for 18 Yale Apt. 2 with 20% down, which uses 7.125%. These are supplied comparison assumptions, not verified current market rates, and do not establish savings against the best financing otherwise available to a buyer. Calculated payments are rounded to the nearest cent. Annual savings equal the unrounded monthly difference multiplied by 12, rounded to the nearest dollar.
Illustrated credits are $60,000 except for 18 Yale Apt. 1 with 10% down ($50,000). No seller credit amount has been approved or promised. The full credit is not assumed to be discount points; its allocation between points and other eligible costs must be confirmed. All financing is subject to underwriting, appraisal, property eligibility, loan program contribution limits and lender approval. Mission Realty Advisors at Compass provides real estate services. Ask your lender for a written Loan Estimate and complete financing disclosures.
Learn more: CFPB guide to discount points · Compare mortgage offers.